First-person account & venture-capital signals
I Saw Big-Name Investors—and Became the Cat That Tried to Be a Tiger
A reader's first-person account of buying GFI because Coinbase Ventures and a16z were involved, and the difference between borrowing someone else's conviction and building your own.
Scope and limits: This is a first-person account submitted to GoldfinchClaims. It reflects one investor's own experience, reasoning, and opinions about buying GFI after seeing Coinbase Ventures and a16z linked to Goldfinch. GoldfinchClaims has not independently verified the writer's specific purchase dates, position size, or loss amount, and publishing this essay does not mean GoldfinchClaims is adopting it as our own factual finding about Goldfinch, Coinbase Ventures, or a16z — the venture-funding history and wind-down referenced below are documented separately in the related coverage linked at the end. Nothing here is investment, legal, tax, or professional advice.
I started buying GFI, the token associated with Goldfinch Finance, after seeing respected venture names such as Coinbase Ventures and Andreessen Horowitz (a16z) connected with the project. At the time, that felt like validation.
In crypto, it is easy to treat a well-known investor's name as a shortcut for deep research. If sophisticated firms with experienced teams have backed a protocol, surely they have examined the technology, market, legal risks, token economics, and long-term potential more carefully than an individual investor can. That was my thinking.
Then Goldfinch began winding down, and I was left facing a severe loss. The financial impact hurts, but the larger lesson is about how I made the decision in the first place.
புலியைப் பார்த்து பூனை சூடு போட்டுக் கொண்டதாம்
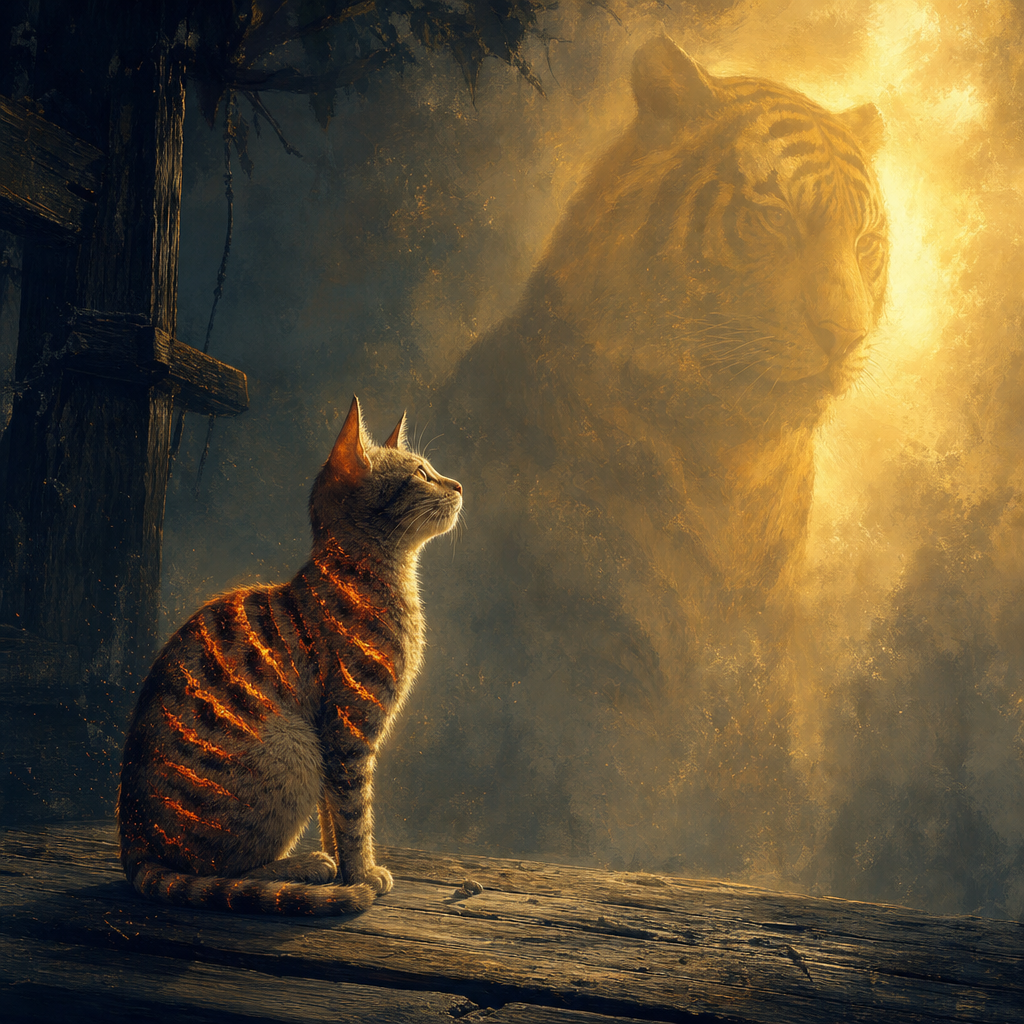
"The cat saw the tiger and branded itself." — A Tamil proverb
The proverb describes a cat that sees a tiger's stripes and tries to imitate them by burning marks onto its own body. Instead of becoming a tiger, the cat only injures itself. That is how I now view my investment decision.
The danger of borrowed conviction
Seeing Coinbase Ventures and a16z associated with Goldfinch gave me confidence — but it was not necessarily my confidence. It was borrowed conviction. I did not fully distinguish between several very different things: a venture firm making an early-stage investment in a company or protocol; a venture firm holding equity, tokens, warrants, or another type of exposure; a fund's investment thesis at one particular time; a public token buyer purchasing GFI later in the open market; and a project's product potential versus the long-term value of its token. Those are not the same trade.
A venture investor may enter at a different valuation, under different terms, with information rights, governance influence, vesting schedules, liquidity constraints, portfolio hedging, and an ability to absorb losses across many investments. A retail buyer in the secondary market often has none of those advantages. I saw the tiger's stripes — the prestigious names, the institutional backing, the sophisticated branding — and assumed that copying the visible move would produce a similar outcome. It did not.
A good project is not automatically a good token
One of crypto's hardest lessons is that product quality, investor pedigree, and token performance can diverge sharply. A protocol can have a thoughtful mission, attract talented builders, raise money from major funds, launch partnerships, and build real infrastructure — yet its token can still perform poorly, because token holders may lack a clear claim on protocol revenue, supply unlocks can overwhelm demand, regulatory or credit or liquidity risks can rise, the addressable market can prove smaller than expected, the team may decide winding down is more responsible than continuing, or a market cycle can crush even a legitimate project.
The important point is not that big investors are always wrong. They are not. It is that their participation should be a starting point for research, not the conclusion.
What I should have asked
Before buying, I should have been able to clearly answer questions such as: what does the token actually do; who owns the token supply and what are the unlock schedules; what is the protocol's real business model; what risks are unique to the protocol; what exactly did institutional investors invest in and on what terms; what would invalidate the investment thesis; and how much could I afford to lose. These questions do not guarantee a winning investment, but they force an investor to own the decision rather than outsourcing judgment to logos on a funding announcement.
Venture capital is not a buy signal
The crypto market often turns fundraising news into a retail buy signal. That is a mistake. Venture firms are paid to take many high-risk bets and expect some to fail; their portfolio model is built around a small number of exceptional winners offsetting many losses. An individual investor's situation is usually very different — one concentrated position can be emotionally and financially devastating for a retail buyer, where a fund treats the same failure as a normal outcome within a diversified portfolio. The same headline can mean "one asymmetric bet among many" to a fund and "institutional validation, so it must be safe" to a retail buyer. That gap is where many bad decisions begin.
Losses are painful, but lessons matter
I do not write this to blame Goldfinch, Coinbase Ventures, a16z, or any other investor for my decision. A project winding down can be disappointing and financially painful, but buying a token was ultimately my choice. The responsibility is mine. My mistake was not simply being wrong about a token — every investor will be wrong sometimes. My deeper mistake was confusing someone else's investment decision with my own research process. I treated institutional participation as a substitute for understanding the asset. It was not.
"The cat saw the tiger and branded itself." I saw prominent venture investors and assumed that following their apparent path would make my investment strong. But I did not have their entry terms, their portfolio diversification, their access to information, their risk controls, or their capacity to lose. I copied the appearance of conviction without building conviction of my own.
What I will do differently
Going forward, I want a simpler investment discipline: not buying a token merely because a famous fund backed the project; separating the protocol, the company, and the token, since they may have very different economics; reading token supply schedules, governance rights, treasury disclosures, and actual sources of demand before investing; treating venture funding as one research input, not a recommendation; diversifying and sizing speculative positions so a single wind-down cannot cause severe damage; writing down a thesis, risks, and exit conditions before buying; and staying suspicious of my own fear of missing out.
Crypto rewards excitement, narratives, and fast decisions. But capital preservation requires the opposite: patience, skepticism, position sizing, and an acceptance that even respected investors can back projects that do not succeed. The lesson is not to avoid every risk. The lesson is not to become the cat that saw the tiger and burned itself trying to look the same.
Related coverage
- Our sourced review of Goldfinch's venture backing and exchange-listing timeline, which documents the Coinbase Ventures and a16z funding referenced in this essay.
- GIP-87, the Goldfinch governance proposal that moved core operations into maintenance mode and wind-down
- Our broader framework for separating protocol hype from token-level risk